
When officials at the Federal Reserve meet next month to vote on interest rates, they will have only a partial snapshot of the economy in hand. Fresh inflation data comes out the day after policymakers finalize their rate decision, leaving them without insight into whether price pressures in November continued to accelerate or showed signs of easing.
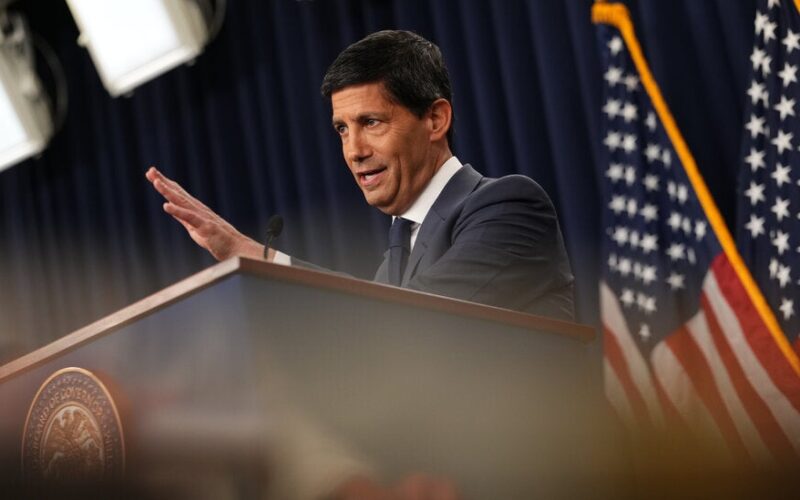
This predicament underscores why officials at the central bank broadly appear on board with a plan hatched by Kevin M. Warsh, the Fed chairman, to reduce the number of meetings convened each year to vote on interest rates.
The changes will be ushered in gradually, beginning next fall. In a revised schedule released on Thursday, the Fed confirmed that its policymakers will meet eight times in 2027, but that the Oct. 25-26 gathering will be “dedicated to the discussion of broad monetary policy strategy issues.”
By 2028, there will be just six meetings accompanied by policy votes, with two others focused on strategy.
Meeting less frequently, and at more evenly spaced intervals, has the clear benefit of giving officials a more consistent flow of economic data to parse when they gather to debate their policy settings. But there are trade-offs that will put more onus on Mr. Warsh to communicate openly about how the Fed is approaching its rate decisions and its thinking about the outlook, something he has so far resisted even as the central bank has embarked on raising rates this year.
“The decision process is more important than the timing,” said Esther George, who served as president of the Federal Reserve Bank of Kansas City from 2011 to 2023. “And this committee is struggling a bit with how to communicate what exactly they mean.”
Since taking over as chairman in May, Mr. Warsh has embraced a different communications style than his predecessors. He has been much more circumspect about what he is willing to share, keeping his views about the economy close to his chest, as well as anything related to the policy outlook. That has resulted in occasional public remarks and abridged news conferences.
In fact, one of his first acts as chairman was to overhaul the Fed’s policy statement that accompanies rate decisions. It now is significantly shorter and less detailed.
The void has been filled by Mr. Warsh’s colleagues, who have continued to vocalize their thinking about how the economy is faring; the extent of the inflation problem that the Fed is facing; and often very explicitly, what the central bank should do with rates to address it.
The dynamic reared up this week in the wake of new inflation data that showed price pressures intensifying more than expected. Officials from across the Fed engaged in what amounted to a public debate about how aggressive the central bank now needs to be in squeezing the economy to get inflation under control.
For William English, a former director of the Fed’s monetary affairs division who is now a professor at Yale University, Mr. Warsh’s communications style is a consequential one that will grow more pronounced as the Fed meets more sparingly.
“He’s giving up a fair amount by communicating as little as he seems to want to communicate, and I worry that’s really not helpful for the public’s understanding of what the committee is trying to achieve,” said Mr. English.
“If you had a committee that was meeting really often, then you don’t necessarily have to communicate as much, because you’re going to be taking another step or not taking another step very soon,” he added. “The longer the gap, the more communication does matter.”
At the turn of next year, for example, there will be a roughly two-month gap between policy votes. According to the new schedule, the Fed’s final gathering, typically scheduled for December, will be on Nov. 16-17, 2027. Officials would next meet Jan. 25-26, 2028, if the tentative schedule holds. Notably, the Fed’s rate moves in the last three years have mostly been in the final quarter of the year.
Fewer gatherings raise the prospects that the Fed will have to move in bigger increments than its typical quarter-point pace to play catch-up if the economic backdrop changes rapidly between rate decisions. It could also mean that impromptu meetings, which in the past have been reserved for crises, might happen more regularly.
Each of these dramatic steps could potentially create a lot of havoc for financial markets if not properly explained. Clearer communication could also help the Fed avoid taking them in the first place, said Donald Kohn, who served as vice- chair of the Fed from 2006 and 2010 when Mr. Warsh was a governor.
If the Fed provided guidance that it was worried about the inflation backdrop, for example, markets would begin to price in additional policy tightening if the data came in worse than expected. “But, if you’re not telling the markets about what you’re worried about and how you’re viewing things, they’re not going to have the ability to get out ahead of you,” said Mr. Kohn.
The meeting schedule is just one facet of a broader overhaul that Mr. Warsh wants in how the Fed communicates. One of five task forces he formed is looking at the range of tools at the central bank’s disposal: from the release of quarterly economic projections by officials known as the “dot plot,” which Mr. Warsh has openly criticized, to the post-policy meeting news conferences and minutes that are released three weeks later.
Kurt Lewis, a former senior Fed adviser who is now head of central bank policy at the investment bank Piper Sandler, said he expects sweeping changes to the dot plot. He anticipates that it could be replaced by some form of an economic forecast, potentially provided by Fed staff instead of policymakers.
Changes to the dot plot would likely require the support of Mr. Warsh’s colleagues. But the chairman would have unilateral authority to decide how often he wants to hold news conferences, for example.
For Mr. Lewis, one thing is probably off limits no matter how much Mr. Warsh’s wants it to change: “No one is going to agree to talk less.”